Tabadulat Trading Instruments
Tabadulat currently promotes the following instruments:
- Halal stocks
- Shariah-compliant ETFs
- Fractional investing
- Islamic savings
Its regulatory permission encompasses shares, units in collective investment funds, government/public financial instruments and Sukuk.
The headline number is an investment universe of 40,000+ stocks and ETFs screened against AAOIFI standards. Tabadulat’s homepage presently markets access across 20+ global markets and describes stocks across the US, Europe, Asia and GCC, while its App Store description makes similar claims.
 Fractional investing should also make expensive US shares accessible to smaller portfolios. Tabadulat advertises fractional investing from any amount.
For diversification beyond individual equities, investors can use Shariah-compliant ETFs. Tabadulat says its ETF universe covers themes and asset classes including global equities, technology, Sukuk and real estate. This is particularly useful for investors who want diversified exposure without having to screen dozens of companies individually.
The final major product is Islamic Savings, which is distinct from the brokerage account. Tabadulat uses Murabaha-based arrangements intended to generate expected profit through Shariah-compliant trade transactions rather than interest.
These savings products start from USD 1,000 and are offered across Bronze, Silver, Gold and Platinum tiers, with amounts up to USD 999,999 and terms of one, three, six or twelve months depending on the selected plan.
Tabadulat Commissions, Spreads and Fees
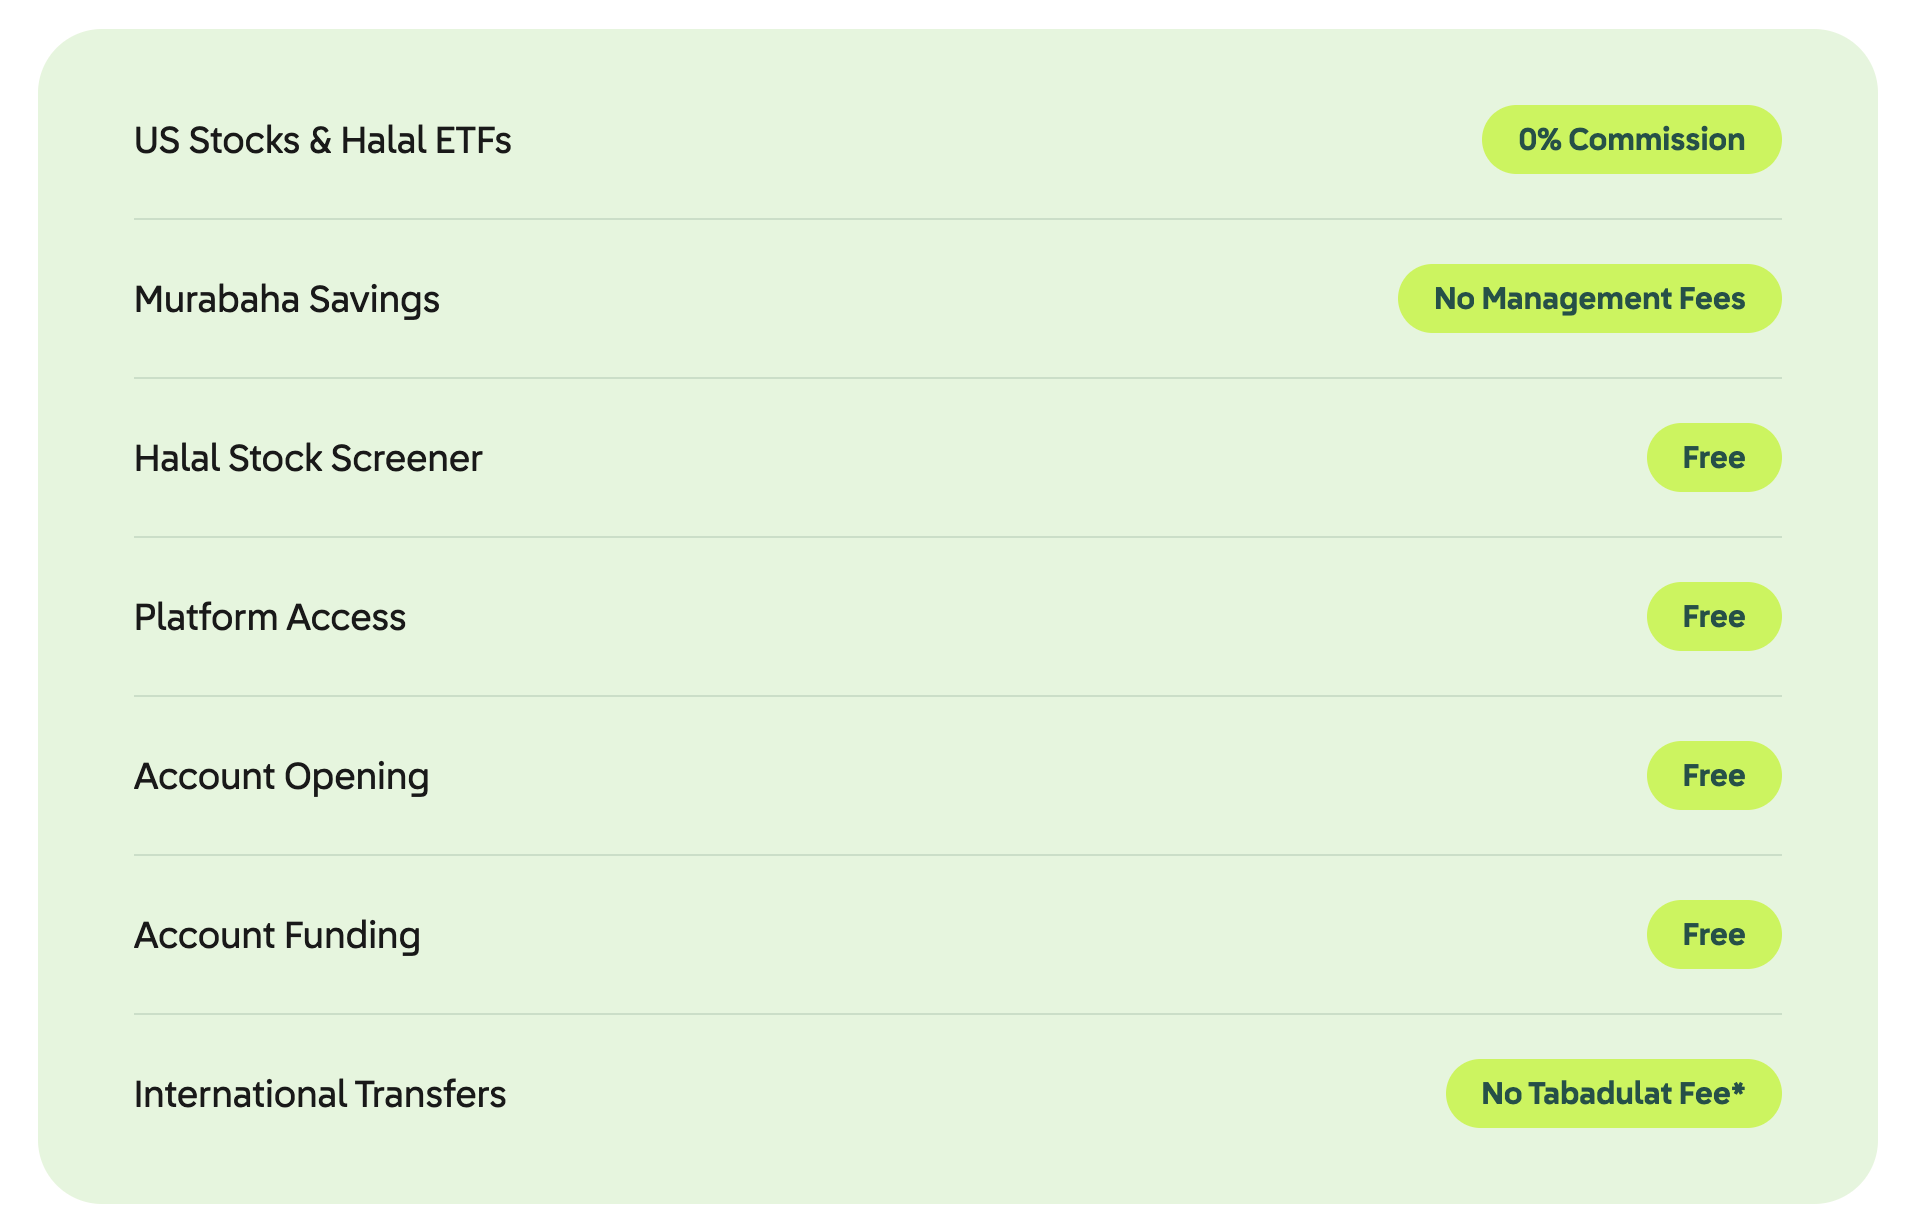
Our analysis found Tabadulat’s pricing to be attractive with 0% commission charged, but the phrase also deserves a little explanation.
The current pricing schedule offers 0% commission on eligible US stocks and halal ETFs. Trades of at least one whole share do not attract Tabadulat’s fractional flat fee. If a trade involves less than one whole share, however, there is a $0.94 fee on each transaction, whether buying or selling.
There is also a 0.25% per year custody fee, calculated daily and charged monthly against the value of the portfolio. Tabadulat itself illustrates this as approximately $2.08 per month on a $10,000 portfolio, or roughly $25 per year before VAT. UAE residents pay 5% VAT on both the fractional-trade fee and custody fee, while Tabadulat says non-UAE residents do not pay that UAE VAT.
That means we would describe Tabadulat as commission-free for qualifying US whole-share trading, rather than completely fee-free. This is an important distinction, but it does not undermine the value proposition. For a long-term investor who buys whole US shares infrequently, a 0.25% annual custody charge is simple to understand and the absence of a conventional trading commission is attractive.
Currency conversion is another potential cost to keep in mind when investing internationally. Tabadulat’s terms provide for conversion between the currency held as the account’s base currency and the currency of an instrument or transaction when required.
There are several genuinely free parts of the service. Tabadulat currently lists account opening, platform access, account funding and the Halal Stock Screener as free, with no monthly subscription.
It also says it does not levy a fee for international transfers, although the sending or receiving bank can still apply third-party charges. Murabaha Savings has no management fee according to the current pricing page.
Non-transparent pricing has come up as an issue across many other brokers. However, Tabadulat does not fall into that category. All of its fees mentioned here are listed transparently on the website for everyone to see.
Tabadulat Deposits & Withdrawals
The regular brokerage account has no minimum deposit, which gives Tabadulat a low barrier to entry. Funding is available by secure bank transfer and the company says multiple currencies can be used.
Tabadulat’s terms require deposits to come from a bank account in the customer’s legal name, and withdrawals must likewise go to an account belonging to the customer; third-party deposits and withdrawals are prohibited. Transfer-count and daily-value limits may also apply.
On the surface, the withdrawal policy is refreshingly straightforward. Tabadulat advertises withdrawals back to a bank account with no brokerage lock-in period and no exit fee.
Cash generated by selling an investment may be available for reinvestment before settlement, but it cannot be withdrawn until the trade has actually settled. The terms also permit Tabadulat to delay a withdrawal for up to eight business days where funds have only recently been deposited and additional time is needed to ensure the payment has cleared.
It is also important not to confuse the liquidity of the investment account with fixed-term Murabaha Savings. Tabadulat’s terms state that early withdrawal from a fixed-term savings plan is not necessarily guaranteed.
Where early withdrawal is permitted, the investor will generally receive the principal but forfeit the profit that would otherwise have been earned for that plan period, and notice periods or other operational constraints can apply.
Overall, deposits and withdrawals look straightforward for a regulated brokerage account, and we particularly like the absence of a brokerage minimum, account-funding fee and standard exit charge. The main caveat is simply to understand the distinction between immediately available cash, unsettled sale proceeds and money committed to a fixed-term Islamic savings arrangement.
Tabadulat Trading Platform
Tabadulat is best described as a mobile-first investing app, rather than an old-school brokerage platform adapted for halal investing.
The app is available through Apple’s App Store and Google Play and combines account opening, funding, stock screening, market data, trading and portfolio monitoring in a single interface.
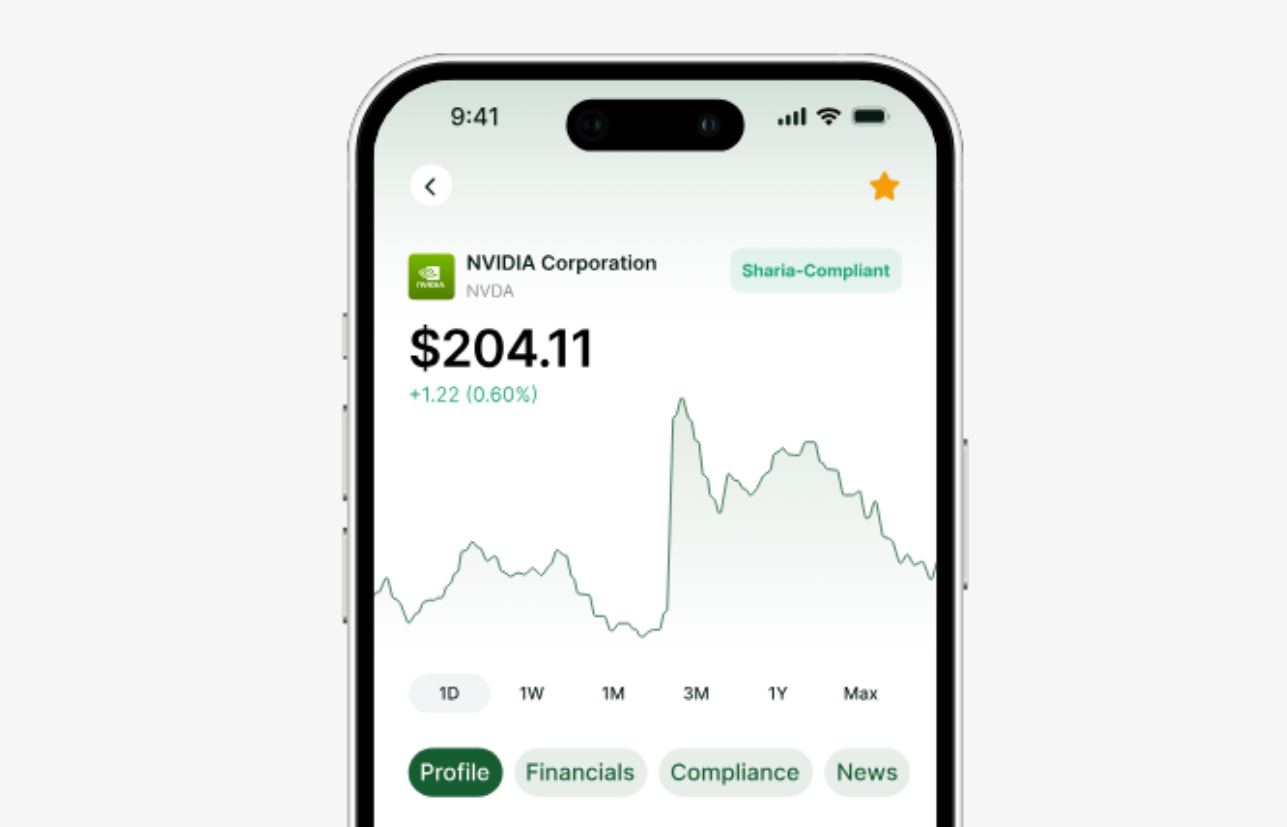
The store listings advertise real-time market data, charts and stock information, portfolio tracking and multi-currency bank-transfer funding.
The biggest strength of the platform is not an enormous collection of active-trading indicators; it is the way Shariah information is embedded directly into the investment workflow.
Search for a stock or ETF and Tabadulat can display its AAOIFI status, which individual screens it passed or failed, and its dividend-purification factor. Holdings are monitored again each month, with investors notified when the Shariah status changes.
That removes much of the friction of checking a ticker in one halal-screening app and then switching to a completely separate brokerage app to place the trade.
There is also an AI feature called Ask Abdul. Tabadulat describes it as an assistant that can answer whether a stock is halal, explain why it passed or failed the screening methodology, and tell the investor what purification may be due.
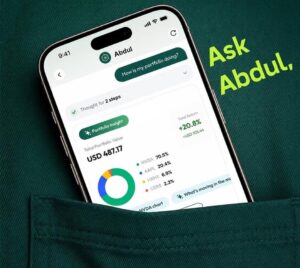
Used appropriately, this is a useful extension of the screener because it makes the underlying compliance information easier for less experienced investors to interpret.
Portfolio monitoring follows the same philosophy. The app presents investment performance and Shariah status in one dashboard rather than treating compliance as a one-off pre-trade exercise. Statements, activity, cash balances and fees are also made available electronically through the secure platform, with Tabadulat’s terms requiring statements at least monthly for active accounts.
One legal detail sophisticated investors should understand is that Tabadulat operates its brokerage service on a matched-principal basis. Its client agreement states that Tabadulat is the counterparty to transactions while simultaneously operating the execution, clearing and settlement process under its FSRA permissions.
It is also explicitly an execution-only service: investors make their own investment decisions rather than receiving personalized portfolio recommendations from Tabadulat.
Tabadulat Account Types
Tabadulat keeps its retail account structure relatively simple. We found no conventional menu of “Classic,” “Premium,” “VIP” account tiers.
Clients are generally onboarded as Retail Clients under the FSRA framework, although the terms allow different regulatory classifications, including Professional Client treatment in appropriate circumstances.
The separate Bronze, Silver, Gold and Platinum names apply to the Islamic Savings/Murabaha proposition rather than to progressively more expensive trading accounts.
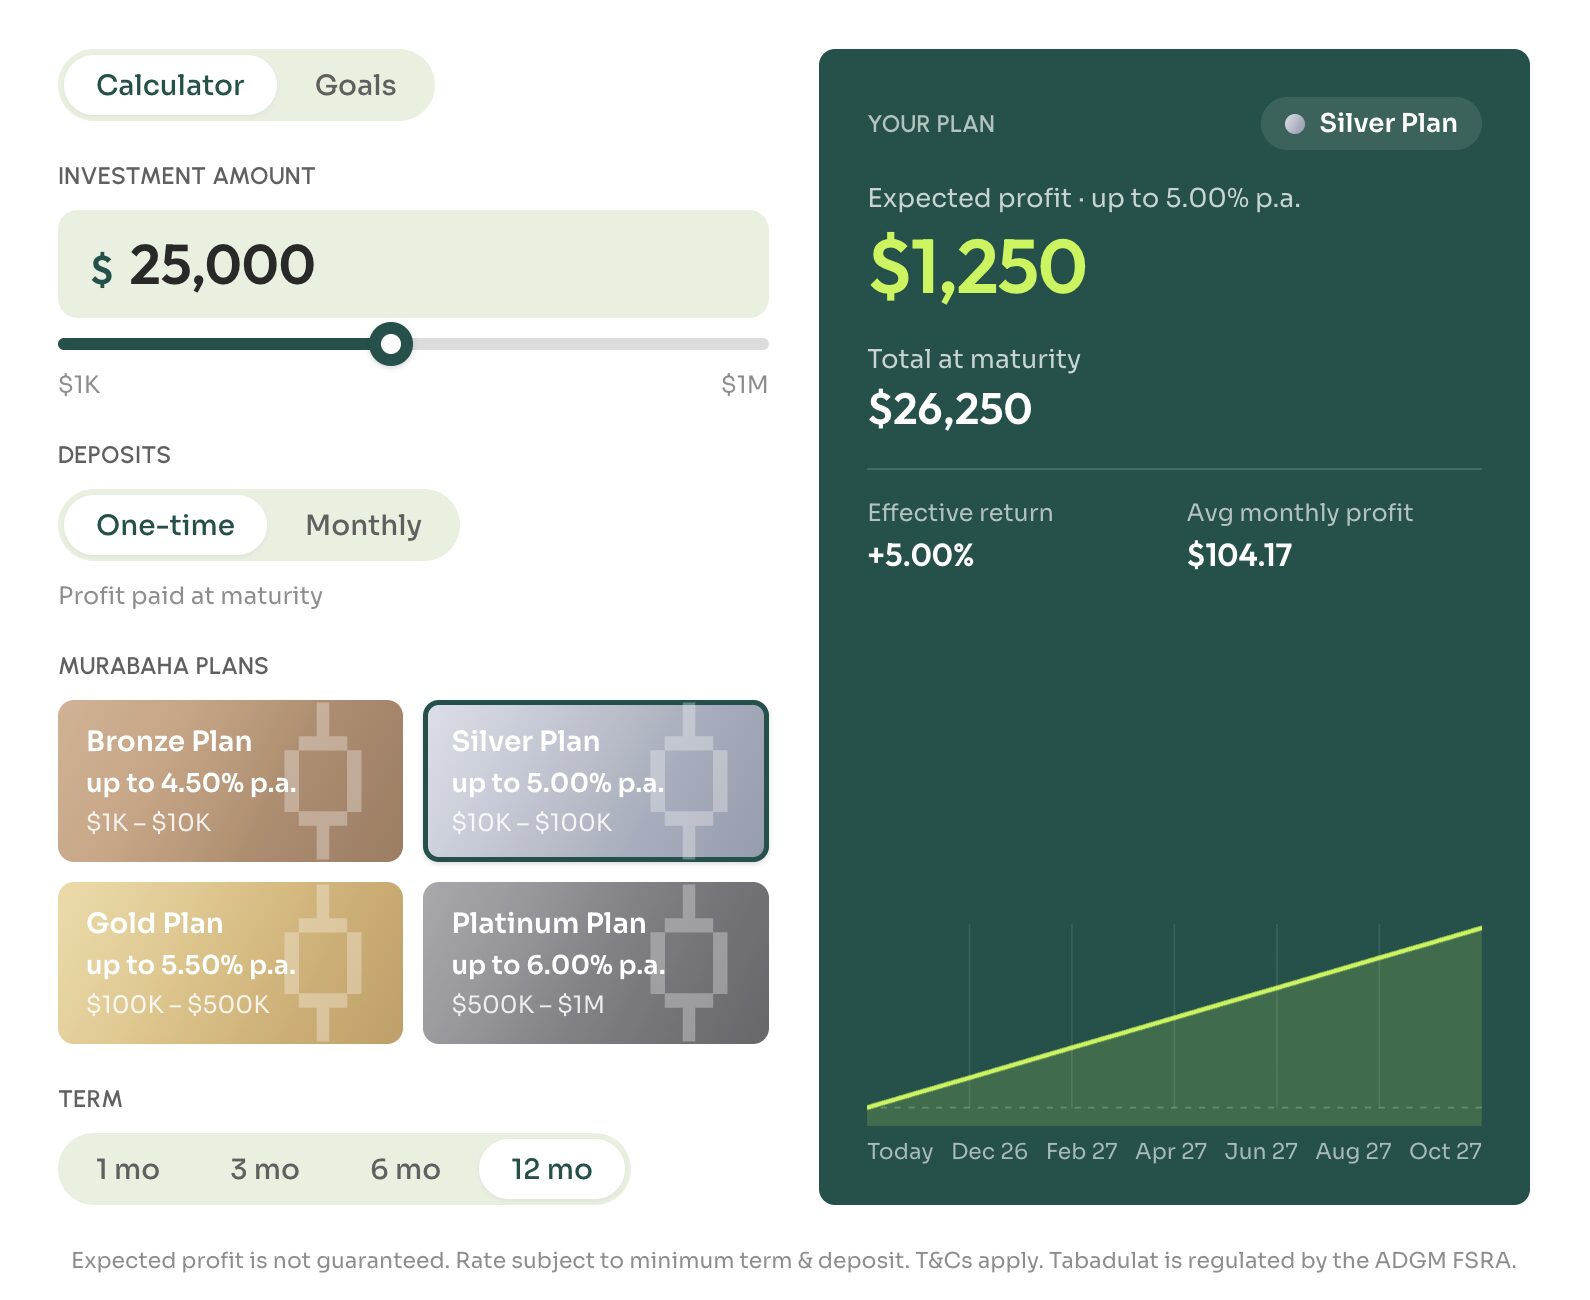
Tabadulat currently says these savings tiers cover investment amounts from USD 1,000 to USD 999,999, with one-, three-, six- and twelve-month tenors available depending on the tier selected.
We prefer this approach to manufacturing account tiers simply for marketing purposes.
For ordinary investors, the important distinction is between the self-directed brokerage account, where stocks and ETFs are bought and sold, and the separate Islamic savings arrangements, where money is placed into Shariah-compliant profit-generating structures for defined terms.
Tabadulat Research & Education
Research Tools
Tabadulat’s research proposition is strongest where it relates directly to halal compliance.
Its free stock screener is the standout tool: the company says more than 40,000 stocks and ETFs are screened, users can inspect individual pass/fail criteria, and each security is reassessed monthly.
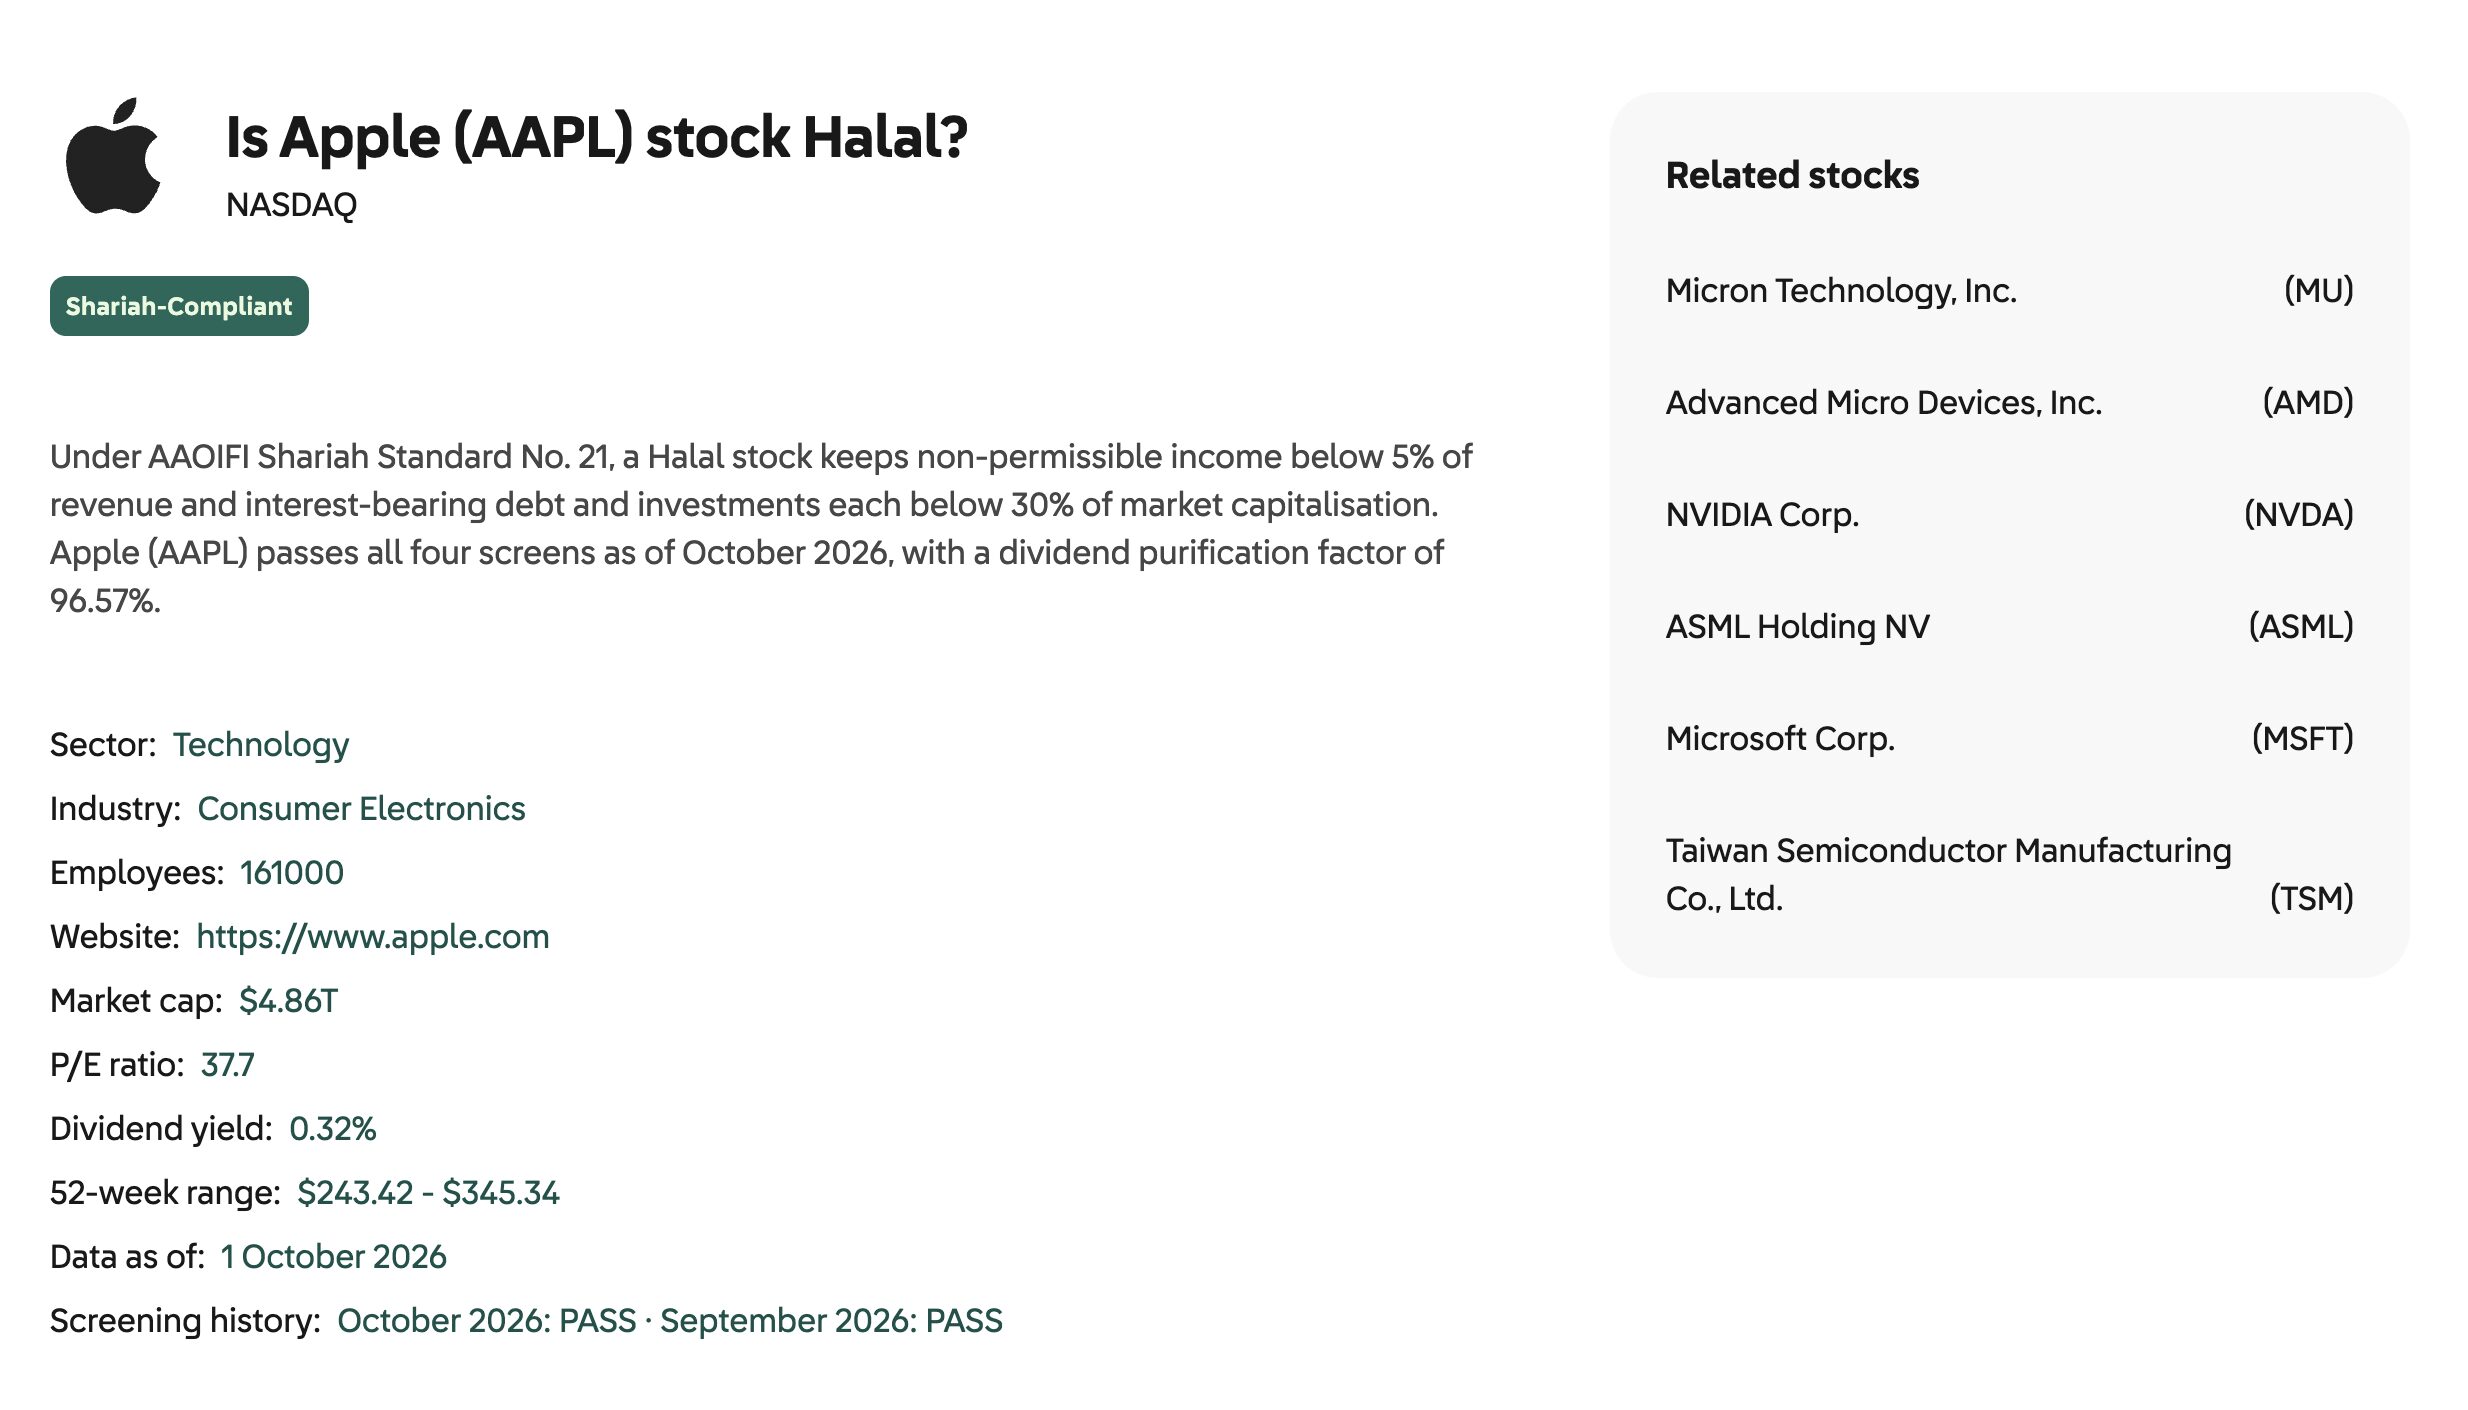
This is a much deeper integration of Shariah data than simply offering a list of “Islamic stocks.”
The underlying screening is reasonably transparent. Alongside excluding businesses operating in prohibited sectors, Tabadulat publishes the major financial thresholds it applies under its AAOIFI methodology: less than 5% non-permissible income and less than 30% of market capitalization respectively for interest-bearing debt and interest-bearing investments.
Its individual stock-screening pages go further by showing which particular tests a company passes or fails and when the assessment was last refreshed.
The purification information is another feature we particularly like. A company can pass Shariah screening while still receiving a small amount of incidental impermissible income.
Tabadulat therefore provides a purification factor intended to help investors identify the relevant portion of dividend income to donate. This is exactly the sort of practical detail that is often missing when a conventional broker simply labels a fund or stock as “Shariah compliant.”
Ask Abdul then gives users a conversational interface to that information, while Tabadulat’s pricing page also advertises free screening and analytics.
Taken together, we think the research suite is more compelling for an investor asking “Is this investment halal, and why?” than for a professional equity analyst looking for institutional-grade financial modelling, consensus-estimate databases or advanced technical-analysis software. The latter is not really Tabadulat’s intended niche.
There is also an important boundary to the research service. Tabadulat is non-advised and execution-only. Screening a stock as Shariah compliant is not the same thing as saying it is a good investment, undervalued or appropriate for a particular customer’s risk tolerance. Investors remain responsible for deciding whether to buy it.
Education
Tabadulat’s Learn section includes webinars, an Investor Hub, educational articles and guidance around halal stock screening, while its blog publishes guides on Islamic finance principles, investment products and comparisons with other platforms.
This material is particularly useful for beginners because it covers concepts that mainstream broker education frequently ignores: AAOIFI screening, Riba, Gharar, Maysir, Murabaha, dividend purification and the practical difference between conventional and Shariah-compliant investing.
Tabadulat Regulation
Regulation is one of the strongest assets of Tabadulat. The official ADGM FSRA register lists Tabadulat Limited as an active financial firm under FSP No. 250032, with the permission effective from November 19, 2025.
Its regulated activities include Engaging in Islamic Financial Business and Dealing in Investments as Principal (Matched) in shares, government and public financial instruments, units in collective investment funds and Sukuk. This is a real financial-services authorization that can be independently checked in the regulator’s register here.
There are also meaningful client-asset rules. Tabadulat’s terms state that client assets are kept separate from the company’s own assets through third-party agents; client money is held in trust through UAE-licensed banks, while investment assets can be held through regulated financial institutions or banks. Client money is subject to FSRA Client Money protections and investments to applicable safe-custody provisions.
From an Islamic-finance perspective, the regulatory authorization is backed by additional layers of governance.
AAOIFI’s own membership directory lists Tabadulat Limited as a UAE member, while the Shariyah Review Bureau announced in August 2025 that it had certified Tabadulat’s brokerage platform, confirming that the digital investment service met the Islamic-finance principles reviewed by SRB. Tabadulat also maintains its own Shariah Supervisory Board.
Those Shariah credentials should not be confused with financial regulation: AAOIFI membership and SRB certification concern Islamic-finance standards and Shariah governance, while the FSRA authorization is the regulatory permission to conduct financial services.
Taken together, however, they provide a notably well-defined governance framework for a broker whose core selling point is halal investing.
Tabadulat Customer Support
Tabadulat provides support through support@tabadulat.com, a website contact form and its platform messaging functionality; its contact page also lists contact@tabadulat.com and the company’s office at Office 3104, Al Tamouh Tower, Al Reem Island, Abu Dhabi.
The website additionally operates a WhatsApp community where customers can connect with the company and other investors.
During our testing, we found Tabadulat’s customer support to be fast and helpful. We received a response within two hours, and the support team answered our questions clearly.
They provided useful assistance with the onboarding process, account setup, and understanding how to set up and use the platform’s stock screener.
Tabadulat: The Bottom Line
Our overall view of Tabadulat is very positive. It solves a genuine problem rather than just rebadging a conventional brokerage account as “Islamic.”
The account itself is built around Shariah compliance. Securities are screened against an AAOIFI methodology, holdings are reassessed, purification data is provided, client cash is structured not to earn conventional interest, and the brokerage operates as a regulated Islamic financial business under the ADGM FSRA.
Add zero commission on eligible US stock trading, no brokerage minimum deposit, fractional investing, a useful halal screener and a clean mobile-first experience, and Tabadulat has a compelling proposition for UAE-based Muslim investors who want to build their own stock and ETF portfolio.
For investors whose priority is genuinely integrated halal investing rather than leverage, CFDs, derivatives or short-term speculation, Tabadulat is one of the most interesting new brokerage propositions we have reviewed in the UAE.
 Written by Sam Reid
 Fact checked by James Smith
 Last updated 1 day ago